Education

Quick summary
- Informal term, not an official scope. "Scope 4" is a label for avoided emissions, which are estimated against a defined alternative scenario. The GHG Protocol does not include them in Scope 1, 2 or 3.
- Separate, never netted. The GHG Protocol and WBCSD keep avoided emissions outside the inventory, and SBTi and ESRS E1 do not let them count towards reduction targets.
- Evidence decides credibility. Claims rest on a complete inventory, eligibility under WBCSD's three gates and a conservative, well-documented reference scenario.
Scope 4 emissions are one of the least settled terms in carbon accounting. The phrase is widely used for avoided emissions, but it is not an official scope: the Greenhouse Gas (GHG) Protocol defines three scopes, and avoided emissions do not sit in any of them.
The methodology has nevertheless developed. On 24 July 2025, the World Business Council for Sustainable Development (WBCSD) published version 2.0 of its Guidance on Avoided Emissions, a structured methodology for assessing and disclosing avoided emissions claims.
This blog explains what Scope 4 means, how avoided emissions are calculated, how standard setters treat them and where claims go wrong.
What are Scope 4 emissions?
Scope 4 is an informal label for avoided emissions: the reductions in GHG emissions that occur when customers use a lower-carbon product or service instead of a higher-carbon alternative. The World Resources Institute (WRI) defines them as emission reductions that occur outside a product's life cycle or value chain, but as a result of the use of that product. WBCSD frames them as the difference between the emissions of a solution and those of the most likely alternative scenario in which the solution is not used.
WRI’s examples include low-temperature detergents, fuel-saving tyres, energy-efficient ball-bearings and teleconferencing services. WBCSD’s guidance uses examples such as LED light bulbs, high-performance glazing and livestock feed. In each case the saving appears in the footprint of the customer, not of the company that made the product.
The label dates back to at least 2013, when WRI listed "scope 4" among the terms used for avoided emissions in a commentary announcing a GHG Protocol survey on whether a standard was needed. In 2019, WRI published Estimating and Reporting the Comparative Emissions Impacts of Products, a neutral framework for estimating a product's impact relative to a situation in which it does not exist. The GHG Protocol has not yet published a dedicated standard for avoided emissions. Its Actions and Market Instruments workstream, which covers avoided emissions among other topics, is developing guidance on how companies report the impacts of actions and market instruments. A white paper published in March 2026 proposed separate reporting statements alongside the physical GHG inventory, but the proposal is still under development and is not a final standard.
Scope 4 vs Scopes 1, 2 and 3: what’s the difference?
The distinction matters because a company's inventory emissions and its estimated avoided emissions can move in opposite directions. A manufacturer that sells more of a low-carbon product may see its own Scope 1, 2 and 3 emissions rise with production, while customers' emissions fall compared with the likely alternative. WBCSD notes that the provider's downstream Scope 3 emissions can overlap with avoided emissions, for example when a new product replaces one the company previously sold, and recommends disclosing that overlap. Scope 3 category 11 (use of sold products) counts only the use-phase emissions of a company's products, never avoided emissions.
How do the GHG Protocol, SBTi and ESRS treat avoided emissions?
Under the GHG Protocol and WBCSD guidance, reporting avoided emissions is optional. Where companies choose to report them, the shared rule is separation.
How do you calculate avoided emissions?
WBCSD sets three eligibility gates that a claim should meet before avoided emissions are calculated and claimed:
- Gate 1: climate action credibility - The company has a recent, publicly disclosed Scope 1, 2 and 3 inventory (third-party verified, except for newer or smaller organisations) and near-term targets aligned, or in the process of aligning, with a 1.5°C pathway.
- Gate 2: latest climate science alignment - The solution has mitigation potential according to recognised sources and is not applied to fossil fuel exploration, extraction, production, distribution or sales. Fossil-derived efficiency solutions are not excluded by default but face additional requirements.
- Gate 3: contribution legitimacy - The solution delivers measurable, significant reductions against the reference scenario that are directly attributable to it. This is assessed qualitatively first, then validated with the calculation results at step 5.
The calculation then follows five steps:
- Identify the timeframe - Assess avoided emissions year on year or on a forward-looking basis, consistent with the reporting period of the GHG inventory.
- Define the reference scenario - This is the most likely alternative the solution replaces. It must fulfil the same function and be specific to the market and region.
- Assess life cycle emissions - Calculate emissions for both the solution and the reference scenario across their full life cycles, using the same functional unit, such as one kilometre driven.
- Calculate avoided emissions - Subtract the solution's life cycle emissions from those of the reference scenario.
- Validate contribution legitimacy - Use the results to confirm that the reduction is significant and directly attributable to the solution.
The example below uses illustrative figures only, in tonnes of carbon dioxide equivalent (tCO₂e).
- Functional unit: heating one home for 10 years.
- Reference scenario: 30 tCO₂e over its life cycle.
- Solution: 18 tCO₂e over its life cycle.
- Avoided emissions per functional unit: 12 tCO₂e.
- Units sold in the reporting period: 1,000.
- Total: 12,000 tCO₂e, the estimated avoided emissions over the 10-year use period of those 1,000 units.
Under the forward-looking approach, this total is reported in the year of sale. Under the year-on-year approach, it is spread across the years of use. It is an estimate that assumes each unit delivers the stated difference over its full life, not a measured reduction for the reporting year. The company's own emissions remain in its Scope 1, 2 and 3 inventory, and the estimated avoided emissions are reported separately, never deducted from it.
Common pitfalls in avoided emissions claims
- A weak reference scenario - WRI gives the example of an energy-efficient tablet that has lower life cycle emissions than a desktop computer. If customers keep using both devices, no emissions are avoided.
- Netting - Treating avoided emissions as a deduction from Scope 1, 2 or 3 totals, or as progress towards SBTi targets, misstates both figures.
- Selective boundaries - WBCSD recommends that companies commit at the overarching organisation level, rather than claiming avoided emissions for one division while others lag.
- Optimistic assumptions - WBCSD's conservativeness principle says that where data is weak, the scenario producing lower avoided emissions should be chosen.
- Unexplained method choice - The attributional method compares the footprints of two products, while the consequential method estimates the change in emissions that a decision actually causes. WRI recommends the consequential method for public claims that may involve market effects. WBCSD permits either but expects the choice to be justified.
How avoided emissions differ from carbon credits
The word "avoidance" also appears in carbon markets, where it describes credits generated by projects that prevent emissions elsewhere. Avoided emissions in the Scope 4 sense are different: they describe the effect of a company's own solutions on other actors' footprints. WBCSD states that its methodology is not meant for direct use in carbon markets or for compensating Scope 1, 2 or 3 inventories. The market-based distinction is covered in carbon avoidance vs carbon removals and in the glossary entry on carbon credits.
How to start assessing avoided emissions
- Complete the inventory first - WRI advises companies to report a complete Scope 1, 2 and 3 inventory alongside any avoided emissions claim, and WBCSD builds this into Gate 1.
- Pilot with one solution - Test a single product or service against the three gates before extending the assessment across the portfolio.
- Use sector guidance - WBCSD has published sector guidance for the built environment and for agriculture and food.
- Disclose the methodology - Report the data sources, system boundaries, time period and baseline alongside the figure.
How Zevero can help
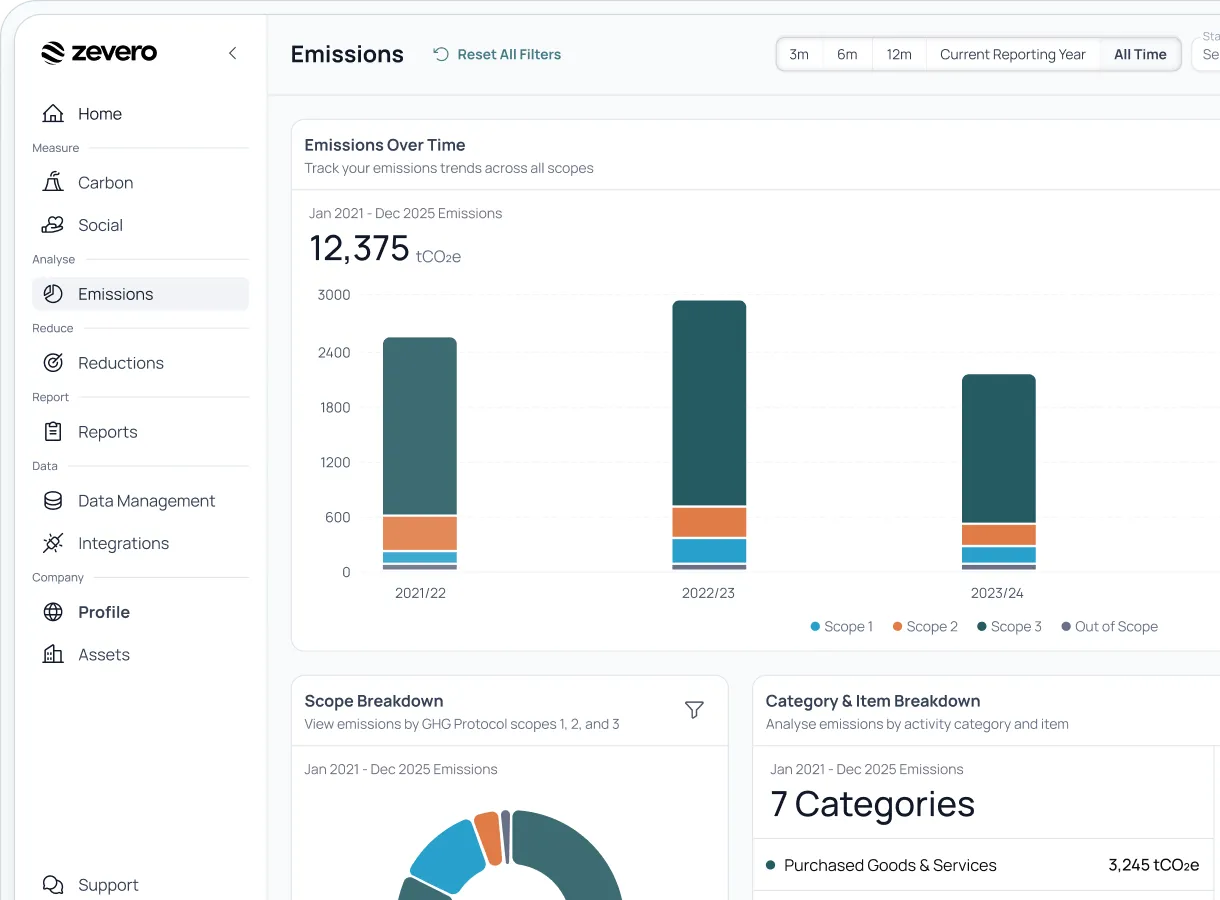
Credible avoided emissions claims start with reliable emissions data, and Zevero, a carbon management platform, supports that foundation. Zevero's corporate carbon footprint measures Scope 1, 2 and 3 emissions using an audit-ready methodology aligned with the GHG Protocol and the International Organization for Standardization (ISO) 14064-1 standard. Zevero's product carbon footprint measures product-level emissions across life cycle stages, in line with the GHG Protocol and ISO 14067. These measurements are a foundation for an avoided emissions assessment, not proof of avoided emissions on their own.
Get in touch to see how Zevero can support a full Scope 1, 2 and 3 inventory.
FAQs
Can a service business make an avoided emissions claim?
How long can a company claim avoided emissions from the same solution?
Do WBCSD's published case studies count as verification?
Can small and mid-sized businesses make claims?
Do negative impacts need to be tracked as well?
Thanks for reading!
Scope 4 Emissions: How Avoided Emissions Are Calculated
Add us as a preferred source
Related posts
Read more

Blog
Jul 29, 2026
How to Set SBTi Targets Under the Net-Zero Standard V2.0
How to Set SBTi Targets Under the Net-Zero Standard V2.0
Read more
Blog
Jul 8, 2026
ESRS Simplified: Where Things Stand in 2026
ESRS Simplified: Where Things Stand in 2026
Read more
Blog
Jul 29, 2026
How to Move Existing SBTi Targets to the V2.0 Standard
How to Move Existing SBTi Targets to the V2.0 Standard
See how Zevero can streamline your carbon reporting
Grow your business and reduce your impact